Church Financial Report Examples for Pastors and Finance Committees
A useful church financial report helps leaders answer three questions: What happened this month? How does it compare with the plan? What money is available for the decisions ahead?
The examples below use real Jade Funds report screenshots from our staging site, with sample data for January 1 through September 30, 2026. They show how to explain income and expenses, budget progress, and fund activity to a pastor or finance committee. The figures are demonstration data, not a real church’s finances.
Start with a short leadership summary
Before handing the committee several pages of detail, give them the few numbers and explanations that frame the meeting.
Summary of the staging sample reports through September 30, 2026
| Measure | January through September |
|---|---|
| Revenue | $131,695 |
| Expenses | $101,285 |
| Income less expenses | $30,410 |
| Total ending fund balance | $107,910 |
| Ending purpose-restricted fund balances | $7,550 |
In this sample, revenue exceeds expenses by $30,410. The $107,910 ending fund balance is a different measure: it also reflects $77,500 shown under “Transfers & other changes.” It should not be presented as income earned during the period or as a bank balance.
A useful meeting note might read: “Income exceeded expenses through September, but it was below the budgeted plan. Review the income comparison and the building and missions fund balances before approving additional spending.”
A summary should make the next question obvious, rather than make the pastor interpret every ledger line.
Example 1 Income and expenses
An income and expense report shows financial activity over a period. In Jade Funds, this report is also described as a Statement of Activities or P&L.
Jade Funds screenshot with staging sample data. January 1 through September 30, 2026. Includes reviewed postings only.
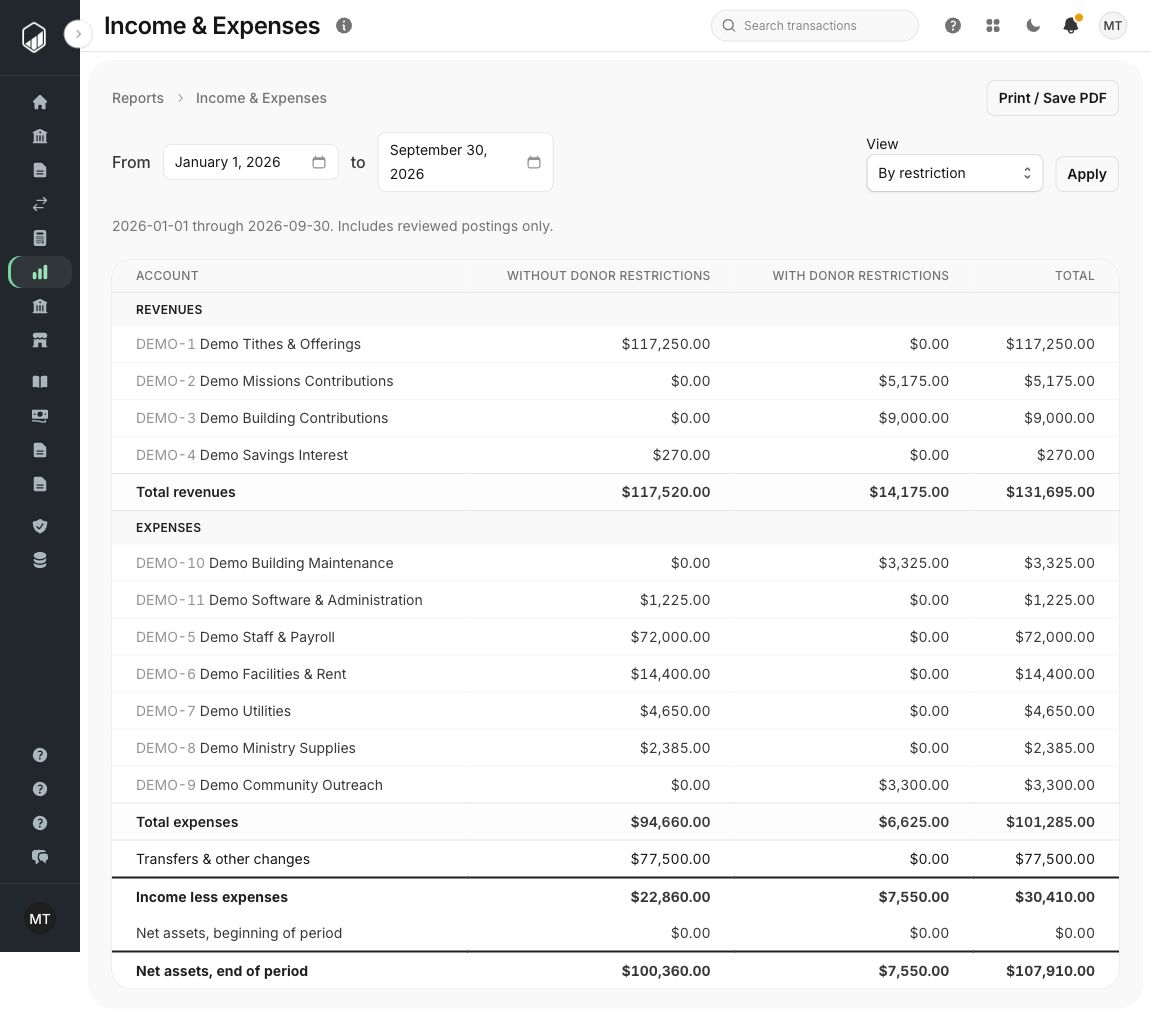
The screenshot shows $117,250 in Demo Tithes & Offerings, $5,175 in Demo Missions Contributions, $9,000 in Demo Building Contributions, and $270 in savings interest. Together, they produce $131,695 in revenue. Expenses total $101,285.
The columns separate activity with and without donor restrictions. That gives leaders context a single total cannot provide. The $30,410 income-less-expenses line explains the period’s result; the separate “Transfers & other changes” line helps explain why ending net assets are larger.
Keep important explanations near the numbers. If facilities spending includes a one-time repair, say so. A committee should not have to guess whether an unusual cost will recur.
Example 2 Budget versus actual
A budget comparison shows how reviewed activity compares with the published plan for the same period.
Jade Funds screenshot with staging sample data. Demo Ministry Budget 2026, January through September. All income and expense accounts.
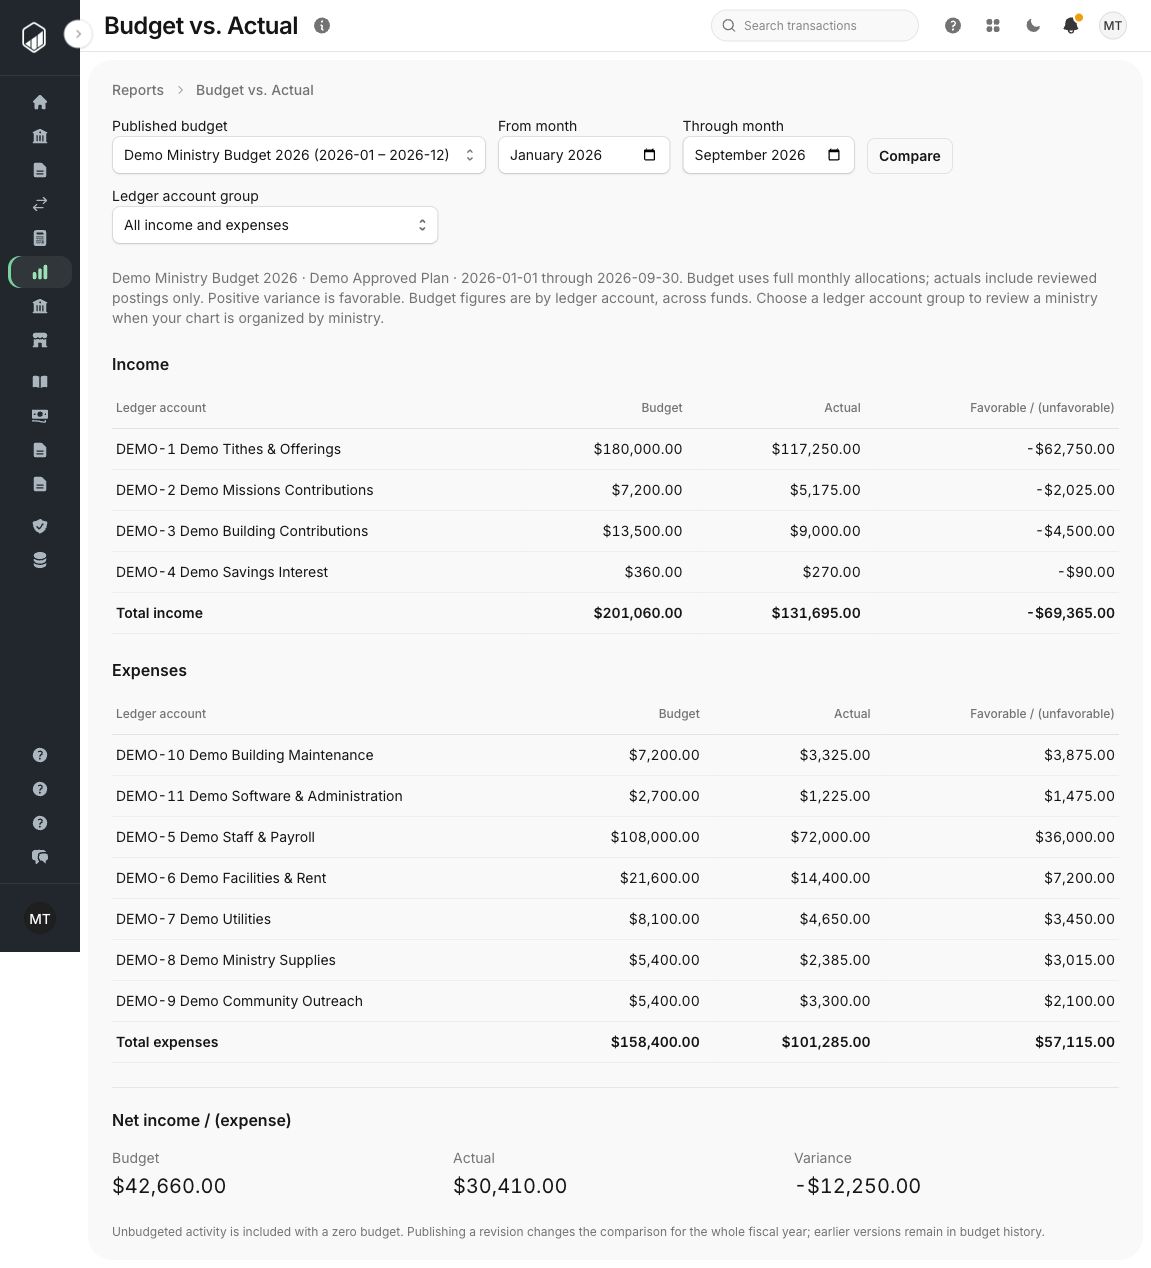
The sample budget planned $201,060 in income and $158,400 in expenses through September. Actual income was $131,695, and actual expenses were $101,285. Income was $69,365 below plan, while expenses were $57,115 below plan.
Lower expenses alone do not tell the whole story. The budgeted income less expenses was $42,660; the actual result was $30,410, a $12,250 unfavorable difference. That is a reason to discuss both giving and spending, rather than treating every positive expense variance as money available for another purchase.
For a specific example, Demo Ministry Supplies has a $5,400 budget through September and $2,385 in reviewed expenses, a $3,015 favorable variance. Ask whether planned purchases are still ahead or whether the ministry’s needs have changed. This comparison is by ledger account across funds; it is not a fund balance or the ministry’s full-year remaining budget.
For planning the budget behind this report, use the church budget planning kit.
Example 3 Fund balances and activity
A fund activity report shows how each balance changed. It connects the purpose of the money with revenue, expenses, and other changes over the period.
Jade Funds screenshot with staging sample data. January 1 through September 30, 2026. Beginning balances, revenue, expenses, transfers and other changes, and ending balances by fund.
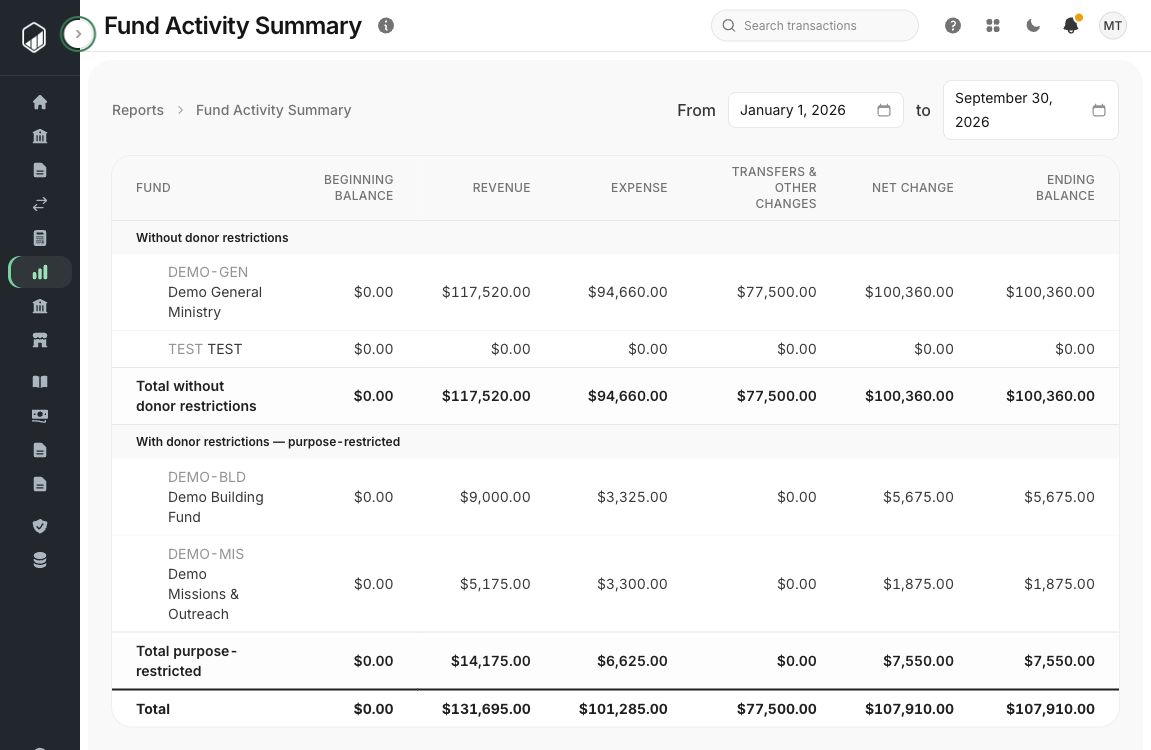
Demo Building Fund shows $9,000 in revenue and $3,325 in expenses, leaving $5,675. Demo Missions & Outreach shows $5,175 in revenue and $3,300 in expenses, leaving $1,875. The two purpose-restricted funds total $7,550.
Demo General Ministry shows $117,520 in revenue, $94,660 in expenses, and $77,500 in transfers and other changes. With the displayed beginning balance of zero, those entries produce its $100,360 ending balance. Adding the purpose-restricted funds gives the $107,910 total.
The report includes other changes explicitly. Do not explain a fund’s ending balance using revenue less expenses alone when those additional entries are present. Fund balances also should not be assumed to equal cash available in a bank account.
Record why a fund exists and what limits its use. A donor’s restriction and a decision by church leadership to set money aside are different situations; avoid treating all named funds as interchangeable. Preserve the supporting gift instructions and church decisions.
See how to track restricted funds for a related discussion.
Match the detail to the audience
The pastor may need a summary and an explanation of upcoming decisions. A ministry leader may need their budget comparison. The finance committee may need those reports plus fund activity, account reconciliation status, and outstanding questions.
Keep individual donor information out of general leadership summaries unless there is a specific authorized need.
Before distributing the reports, check that the periods match, account reconciliation is complete for the relevant period, transactions have the right categories and funds, and unresolved questions are identified. A report generated before review should be labeled accordingly.
Your monthly management report should support your formal financial reporting process. It does not replace financial statements or any review your church requires.
See these questions in Jade Funds
Jade Funds includes income and expense, fund balance, fund activity, financial position, and budget-versus-actual reports. It also supports account reconciliation and transaction review, connecting reporting with the work behind the numbers. Explore Jade Funds features.
Bring the report your pastor or committee already uses and the questions it leaves unanswered. Book a Demo to discuss how Jade Funds fits your church’s reporting workflow.